


What families may want to know before opening one.
Five Questions This Guide Will Help You Answer
Before opening one of the new federal children’s savings accounts, many families may fi nd it helpful
to consider:
- What is this new account, and what was it designed to accomplish?
- How does it compare with more established savings strategies?
- Who may benefit most from these accounts, and who may not?
- What implementation details are still evolving?
- How should this account fi t within a broader financial plan?
New Planning Opportunities Often Raise New Questions
Every few years Congress passes legislation that changes the financial planning landscape. Sometimes those changes modify existing retirement or tax rules. Other times they introduce entirely new planning opportunities designed to encourage saving, investing, or long-term wealth accumulation.
When a new savings vehicle is introduced it naturally generates questions about whether the new option is better than existing strategies or how it might overlap with your current savings plan.
Recently enacted federal legislation created a new type of children’s investment account under Section 530A of the Internal Revenue Code. Throughout the financial industry and in the media, these accounts are commonly referred to as “Trump Accounts” but technically they are a new type of IRA account.
Like many newly enacted financial planning provisions implementation continues to evolve. Although the legislation establishes the overall framework, additional guidance regarding account administration, custodians, investment options, and operational procedures continues to be released. As a result, families may benefit from understanding not only how these accounts work, but also how they compare with existing planning strategies before deciding whether to open one.
The purpose of this guide is not to recommend or discourage the use of these accounts. Instead, it is intended to provide objective planning considerations that may help families evaluate whether a Section 530A children’s savings account deserves a place within their broader financial plan.
What Is a Section 530A Children’s Savings Account?
The Section 530A children’s savings account is a newly authorized investment account created to encourage long-term saving and investing for children beginning early in life. It is best viewed as a retirement savings vehicle for your children.
Eligible children born during the program’s specified eligibility period of January 1, 2025 to December 31, 2028 may qualify for an initial government-funded contribution of $1,000. Only one account is allowed per child. Parents, grandparents, other family members, and certain third parties may also make annual contributions, subject to contribution limits established by law (currently $5,000 per child per year). Certain states, municipalities, and even third parties have also pledged to make contributions to certain qualifying children (which may be based on where the child lives or the family income). The legislation also permits qualifying employers to contribute on behalf of an employee’s child through approved employer-sponsored programs, which will not count as taxable income to the employee recipient. These features distinguish the account from many existing savings vehicles and are among the reasons it has attracted significant public attention.
The accounts will convert to a traditional IRA of the child on January 1 of the year the child turns 18. Investment growth generally occurs on a tax-deferred basis, with future distributions consisting of both after-tax contributions and investment earnings. The investment portion of withdrawals will be taxed as ordinary income at the time of distribution and like other IRA accounts will typically be subject to a 10% penalty if withdrawn before the child reaches age 59 1/2. During the account’s growth period assets must generally be invested in qualifying low-cost index funds as defined under the legislation.
Another notable feature is that these accounts are not subject to earned income requirements or contributor income limitations that apply to most tax-advantaged retirement accounts.
The long investment horizon is one of the account’s primary objectives. By encouraging investing during childhood, lawmakers hope that decades of potential compounded growth may help participating children begin adulthood with a stronger financial foundation.
While the overall structure has been established, many administrative details continue to evolve. Financial institutions are still implementing procedures, additional regulatory guidance is expected, and certain operational questions remain unanswered. As with many newly enacted financial planning provisions, the practical application of these accounts will likely become clearer over time.
A Brief Historical Perspective
Although these accounts are new, the underlying concept is not.
For many years, policymakers, economists, and financial professionals have discussed ways to encourage investing at an earlier age by providing children with an initial financial asset that has the potential to grow over time. Various proposals have appeared under different names and with different structures, but many have shared a common objective: promoting long-term savings through the power of compounding.
The recently enacted Section 530A account represents one approach to that broader concept. Regardless of its legislative origins or public nickname, families evaluating the account today face the same practical question they would ask about any financial planning opportunity:
Does this account meaningfully improve our family’s long-term financial strategy?
That question is often more valuable than simply asking whether the account itself is “good” or “bad.”
However, if your child qualifies for a contribution of “free money” from the federal government or a third party it is generally advisable to open the account to receive that contribution. Whether you continue to fund the account beyond that may be based on the following considerations.
How Does It Compare with Existing Savings Strategies?
One of the most common misconceptions surrounding newly created financial accounts is that they replace existing planning strategies.
In reality these new accounts simply provide another option. For some families, a Section 530A account may complement an existing education savings strategy. For others, continuing to prioritize retirement savings, a 529 education savings plan, a custodial investment account, or another planning strategy may remain the more appropriate choice.
Understanding those trade-offs is where comprehensive financial planning becomes especially valuable.
Comparing the Section 530A Account to Other Savings Strategies
When evaluating a newly created savings vehicle, one of the first questions many families ask is whether it is “better” than existing options.
The answer, in most cases, is it depends.
Each type of account was created to accomplish a different objective. While there may be overlap, no single account is likely to be the ideal solution for every family or every financial goal.
Rather than asking which account is “best,” it may be more helpful to ask which account is best suited for the purpose the savings are intended to serve.
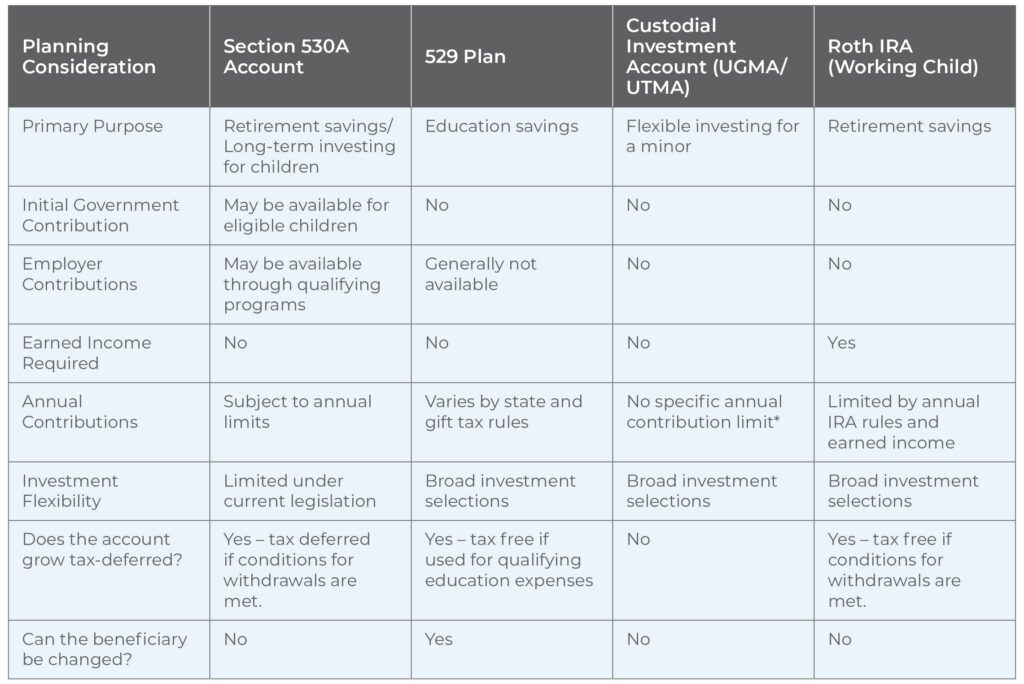
*Gift tax considerations may apply.
While comparison tables can be helpful, they rarely tell the whole story. Financial planning involves understanding how each option works together rather than evaluating any one account in isolation.
Five Questions Families May Want to Ask Before Opening One
Perhaps the greatest value of a new planning opportunity is not the account itself, but the conversation it creates.
Before opening a Section 530A account, families may benefit from asking several broader planning questions.
1. Are We Already Prioritizing Our Most Important Financial Goals?
One of the first considerations is whether opening another account should take priority over other financial objectives.
For many households, strengthening an existing financial foundation may provide greater long-term value.
Examples include:
- Contributing enough to an employer retirement plan to receive the full company match.
- Building an emergency reserve.
- Paying down higher-interest debt.
- Maximizing Health Savings Account contributions when appropriate.
- Funding existing college savings goals.
A new account should generally complement an existing financial plan rather than compete with higher-priority objectives.
2. What Is the Money Intended to Accomplish?
The answer to this question often determines which account deserves consideration.
Will these assets ultimately be used for:
- Higher education?
- Long-term investing?
- Retirement?
- Purchasing a first home?
- General financial flexibility during adulthood?
Different accounts were designed for different purposes. Selecting the account should follow the objective—not the other way around.
3. How Important Is Flexibility?
Every tax-advantaged account provides benefits in exchange for certain rules.
Some restrict how assets may be invested.
Others limit when withdrawals may occur.
Still others provide significant tax advantages while reducing flexibility.
Understanding those trade-offs before opening an account may help avoid unintended surprises years later.
4, Could an Existing Strategy Better Meet Our Goals?
One of the more interesting aspects of the new Section 530A account is that it enters a landscape already filled with well-established planning tools.
For example:
If education funding is the primary goal, a 529 education savings plan may continue to offer significant advantages.
If flexibility is the priority, a custodial investment account may deserve consideration.
If a teenager has earned income from employment, a Roth IRA may provide powerful long-term retirement benefits.
In some situations, the best answer may not involve choosing one account over another. Instead, families may determine that several strategies working together provide greater flexibility than relying on a single solution.
5. Are We Making This Decision Based on Headlines or Our Financial Plan?
Whenever Congress introduces a new savings opportunity, it naturally receives significant attention from the media, financial commentators, and investment firms.
That increased visibility often creates awareness—but it can also create urgency.
Financial planning decisions rarely need to be made quickly.
Instead, they often benefit from thoughtful evaluation, careful comparison, and an understanding of how a new strategy fits alongside existing goals.
Whether a Section 530A account ultimately becomes an important planning tool or simply another available option will depend on each family’s circumstances—not on the amount of media attention it receives.
Illustrative Case Study
Two Families. Two Different Answers.
(For Illustrative Purposes Only)
Michael and Sarah recently welcomed their first child.
Like many new parents, they began researching the new Section 530A children’s savings accounts after hearing about them in the news.
Initially, they assumed opening the account immediately was the obvious choice.
After meeting with their financial advisor, however, the conversation became much broader.
The couple was already contributing enough to receive their employer retirement plan matches but had not yet established a dedicated education savings strategy. They also planned to purchase a larger home within the next several years.
Rather than focusing solely on the new account, they evaluated several alternatives, including a 529 education savings plan, increasing retirement contributions, and opening a Section 530A account if eligible for the initial contribution from the government.
Ultimately, they decided to pursue a combination of strategies rather than relying exclusively on one account.
For another family with different priorities, income, tax considerations, or education goals, the recommendation could have been entirely different.
The lesson was not that one account was superior.
It was that the planning process—rather than the account itself—led to a more informed decision.
What We Still Don’t Know
Like many newly enacted financial planning provisions, the Section 530A children’s savings accounts continue to evolve.
While the legislation establishes the overall framework, several operational details are still being implemented by federal agencies, financial institutions, and account providers. As additional guidance is released, families and advisors should gain greater clarity regarding the day-to-day administration of these accounts.
Areas that continue to develop include:
- Which financial institutions will initially offer Section 530A accounts.
- Account opening procedures and custodial requirements.
- Administrative and reporting requirements.
- Investment implementation and available fund options.
- Employer-sponsored contribution programs.
- Additional IRS and Treasury guidance regarding account administration and distributions.
As with any new legislation, implementation often takes time. Families considering these accounts may benefit from staying informed as additional guidance becomes available rather than feeling pressured to make an immediate decision.
Key Takeaways
Before opening a Section 530A children’s savings account, families may wish to remember five important principles:
New does not necessarily mean better. New legislation often creates planning opportunities, but not every opportunity is appropriate for every family.
Every account has a purpose. Understanding what you are trying to accomplish is often more important than selecting a particular account.
Financial planning involves trade-offs. Tax advantages, flexibility, contribution limits, and long-term objectives should all be considered together.
Implementation continues to evolve. Because these accounts are new, additional administrative guidance and operational details are still being developed.
A comprehensive financial plan should guide the decision. The most effective planning strategies typically result from coordinating multiple financial decisions rather than focusing on any one account.
You should open an account if your child qualifies for a contribution by the government or a third party. Whether you fund the account in addition to the initial contributions is up to you.
Conclusion
The introduction of the Section 530A children’s savings account adds another planning tool to an already broad landscape of savings and investment strategies. For some families, it may become a valuable complement to an existing financial plan. For others, more established approaches—such as retirement savings, 529 education savings plans, custodial investment accounts, or other gifting strategies—may continue to better support their objectives.
The introduction of a new account, however, does not change the fundamental principles of sound financial planning.
Thoughtful planning begins by identifying your family’s goals, understanding the available options, evaluating the trade-offs, and selecting the strategies that work together to support those objectives. The “best” account is rarely determined by a headline, a legislative change, or a single tax benefit. Instead, it is determined by how well it fits within your family’s broader financial picture.
At Waverly Advisors, we believe financial planning is most effective when viewed holistically. Rather than evaluating individual accounts in isolation, we encourage families to consider how investment decisions, tax planning, education funding, retirement preparation, estate planning, and charitable goals work together over time. That comprehensive perspective helps create a planning strategy that can adapt as life changes and new opportunities emerge.
As additional guidance regarding Section 530A accounts continues to develop, families may benefit from periodically reviewing whether these accounts fit within their evolving financial plan. For some, the answer may be yes. For others, another strategy may be more appropriate.
The most important decision is not whether to open a new account.
It is whether every financial decision you make today is helping move your family closer to the future you want to create tomorrow.
If you would like more information about the terms and strategies discussed in this guide, or if you’re ready to explore how they apply to your specific situation, contact Waverly Advisors. With experience working with individuals, families, and executives managing significant wealth, we specialize in creating tailored strategies with the goal to help you grow, protect, and transfer your assets effectively.

